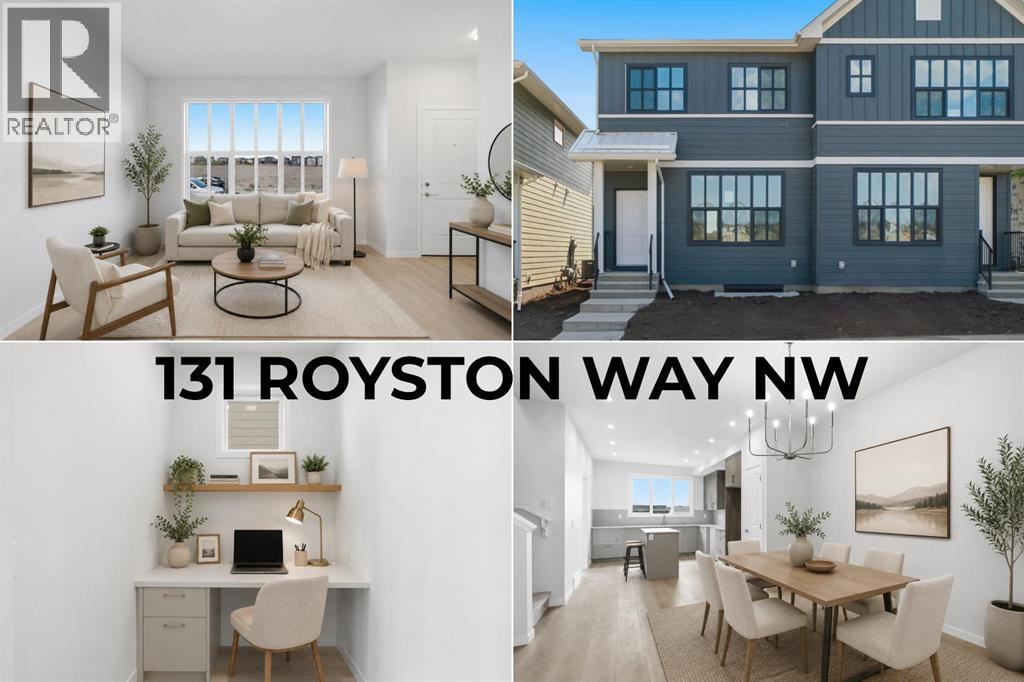
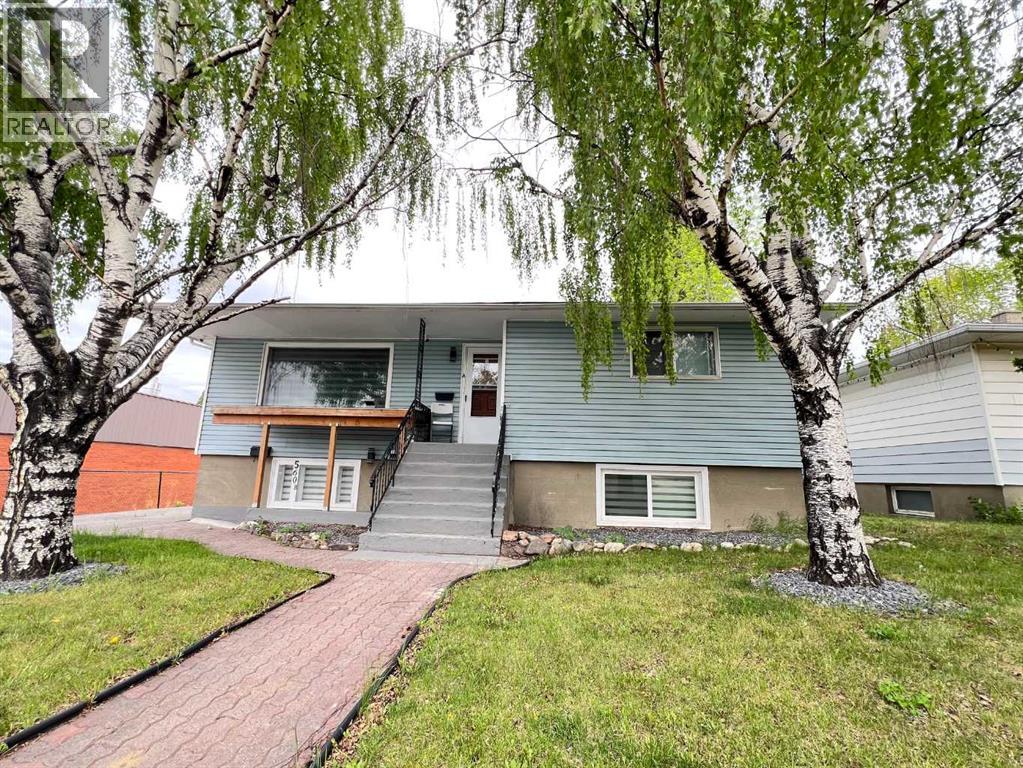
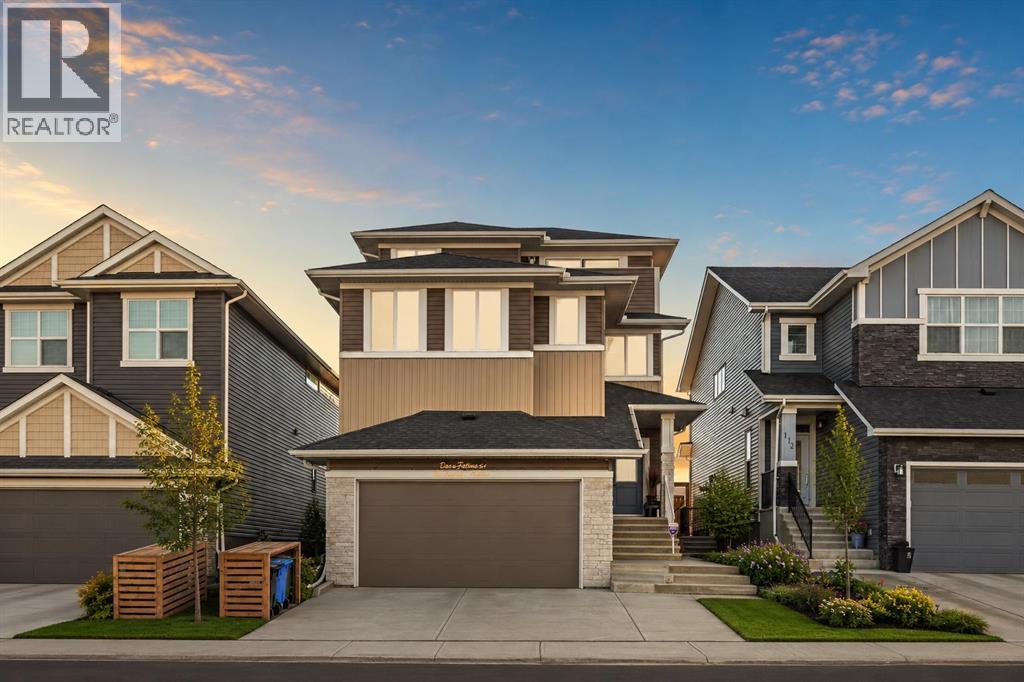
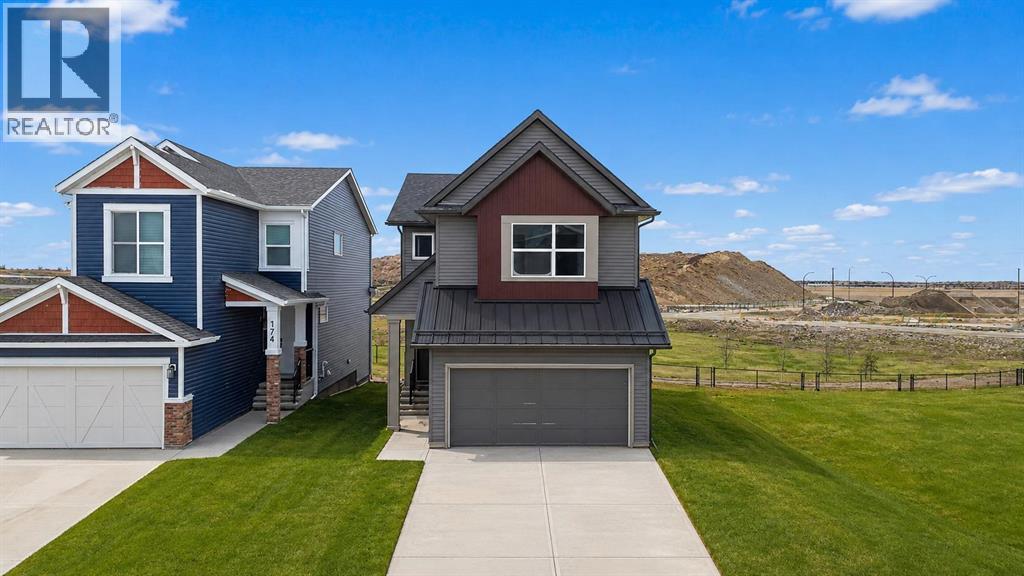
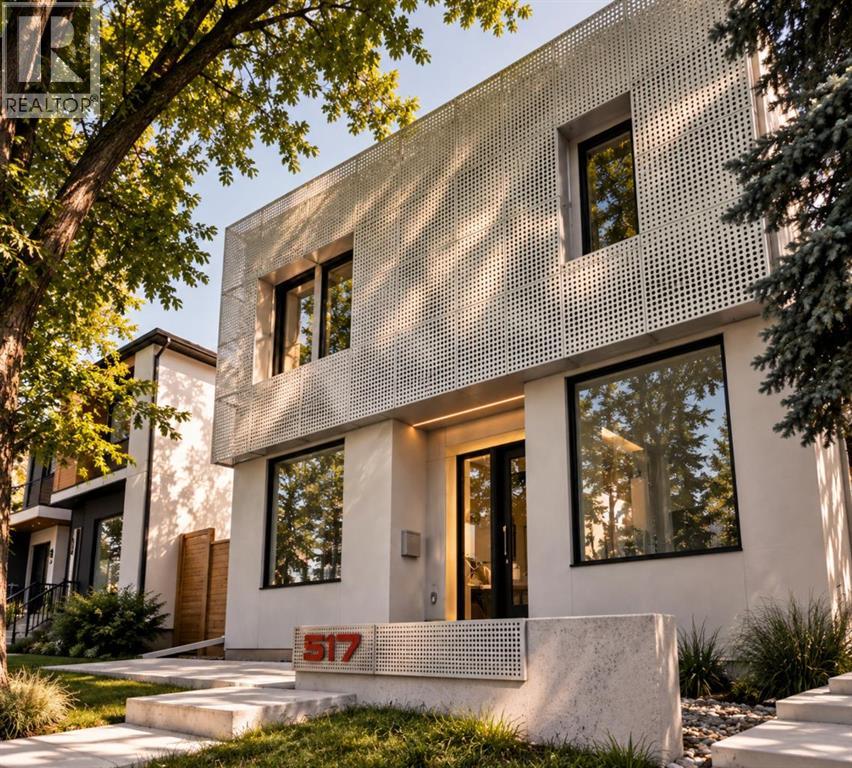
A mortgage-helper search looks for a home where suite rent might help with ownership costs. These listings are candidates identified from MLS® information, not certified rentals or verified cash-flow plans. Establish the suite's status, likely expenses and financing before deciding what contribution you can rely on.
How lenders treat suite income
Ask your chosen lender how it would treat rental income for this specific property and mortgage product. It may need approval records, an appraisal, a lease or other evidence. Do not assume a fixed share of rent counts, or that pre-approval means this home is approved. Confirm the lender's property review before your financing condition expires. The Financial Consumer Agency of Canada explains the limits of pre-approval.
What rent to expect
We do not publish suite rent estimates on individual listings. Rent depends on unit size, entrance type, parking, finish, utilities and current Calgary vacancy — a REALTOR® can pull recent comparable rents for a specific property. Anchor your underwriting to actual rented comps, not an average.
Due diligence checklist
- Available building, development (where applicable) and trade permit records, including completion status.
- Confirmation the property is on the City of Calgary Secondary Suite Registry.
- A qualified inspection of current condition, including escape routes, fire protection and mechanical systems.
- Written confirmation of how your lender will assess this property and any rental income.
- Landlord insurance quote before firming up conditions.
LegalSuites.ca reads CREA DDF® listing remarks and structured fields to interpret each listing's suite status. That is a lead for discovery — not a legal determination. Before writing an offer, confirm any suite against the City of Calgary secondary-suite information page and its Secondary Suite Registry, and engage a licensed REALTOR® and Alberta-qualified inspector.